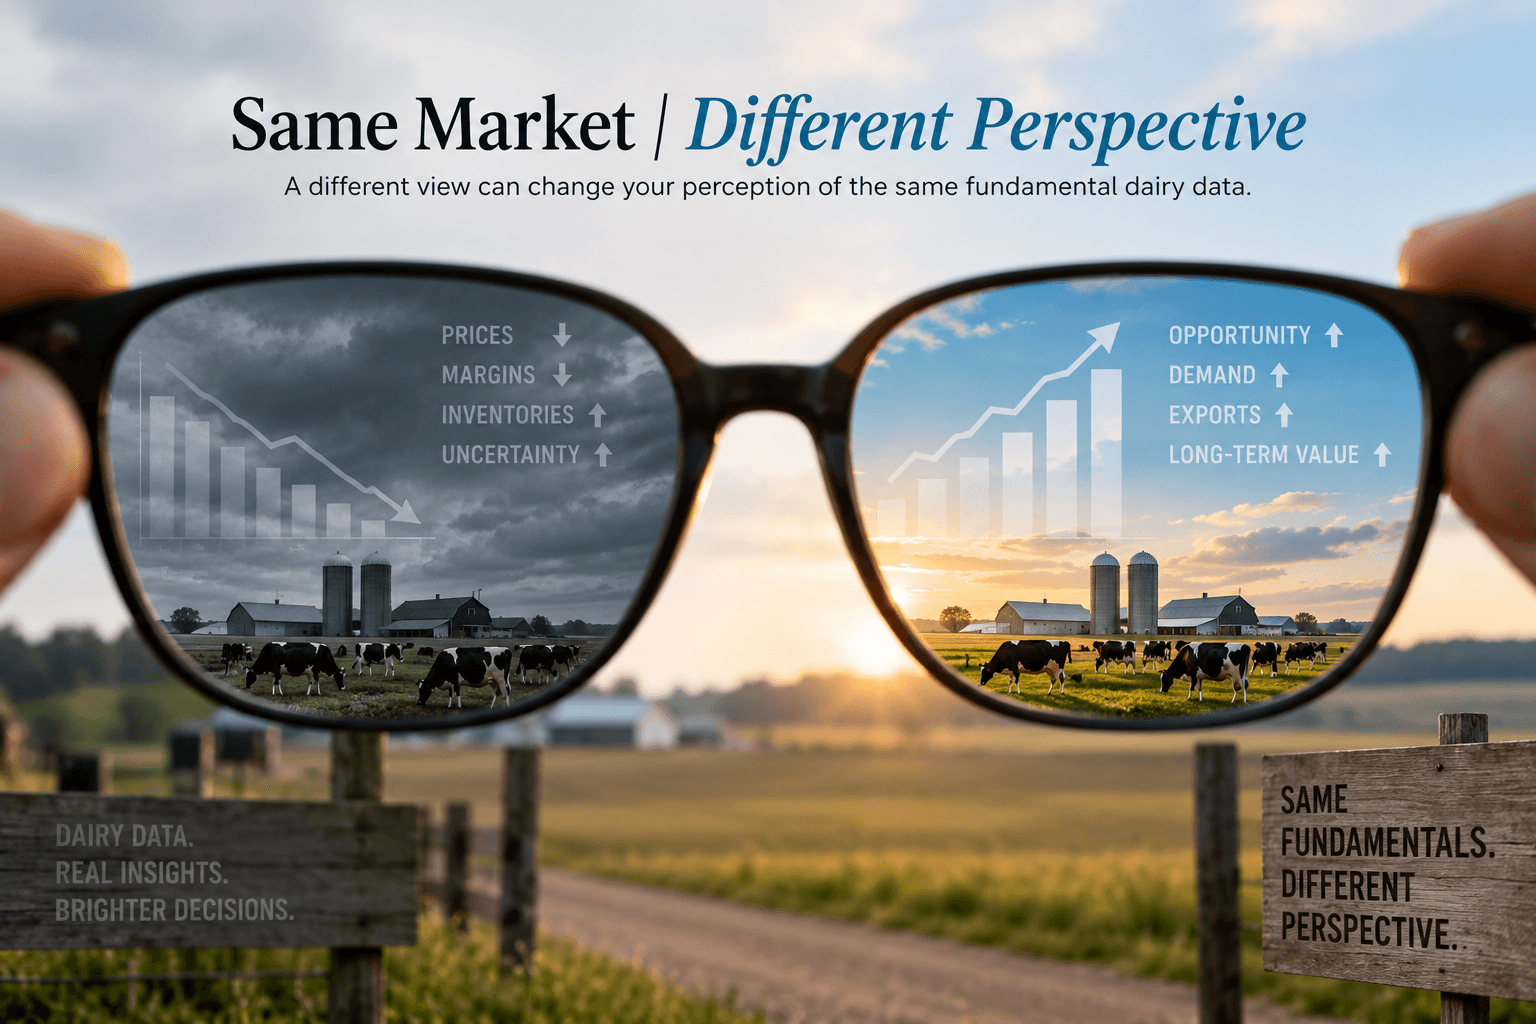
Same Market | Different Perspective
Last week was calm, almost quiet. Our partners seem comfortable with their positions relative to what they expect from the market, and we see very few traders, producers or end users who need any last-minute execution. How different the world looked a year ago. We got that reminder by surprise. A notification told us someone had liked A Market Drowning in Milk, an update we posted on LinkedIn 11 months ago. We wondered why anyone would revisit a post that old, so we asked what had triggered it. The reader told us he was worried about a market that is still drowning in milk.
But is it? Talk to anyone in the market today and their concern is milk volumes drying up, not too much milk. Right?
We had a very long analysis ready to answer that question, backed by graphs, tables and datasheets. Unfortunately, poor battery management and a few frustrated keystrokes lost most of it. So, to make a long story short: in terms of supply and demand, the market we face today isn't that different from a year ago. But how we, and most people, perceive it is almost 180 degrees opposite.
Liquids: More milk, fewer nerves
Last year we wrote that the market was drowning in milk. Processors didn't know what to make and were desperately looking for bids. Demand for commodities seemed to have evaporated. Cream prices traded at € 6000+ (today € 5000) and SMC prices sat at € 1600 (today € 3000+). Yet milk collection data suggests Europe as a whole probably has more milk to process today than 12 months ago. France reports +1% YoY, and Germany is still at +1.4%. The UK is reporting a lot less, and Ireland seems down as well. But ask around in the Netherlands, Belgium and Denmark, and collections there are still ahead of last year. Germany is +5.4% YtD, so the chance that it ends the year with a YoY decline is next to zero.
Western Europe is processing more milk than it was doing last year. It's just doing so a lot more comfortably. Talk to a processor and they're far less nervous than a year ago. The price level represents todays collection numbers; the sentiment doesn't. If mik volumes fall back to last years levels as some expect, its good to remember that last years cream levels dropped to € 4000 by the end over November and € 3100 during Christmas.
So why does the market feel tighter? Why is our partner field so much more relaxed? We'd argue it comes down to one thing: how people see the forward curve. Last year, commodity prices stepped down every day, and every missed sale of milk or cream was another hit to your financial book Cream prices in july still sat at € 9000+ and by the beginning of September at € 8000. July to december took € 6000,- a mt of the cream prices, that at € 1000 delcine a month, a € 250,- decline a week, a € 50,- decline a day. Every day of missing a sale was another financial hit.
But after six months of largely sideways pricing, that urgency is gone. If you don't sell today, you'll probably sell tomorrow at roughly the same price. Last year, missing a week of sales could cost a company millions. Today it might cost you a good lunch. That gives sellers a much healthier timeframe for their decisions.
Butter: Lower prices, calmer heads
Let's do the same exercise for butter. Last year stocks were building fast and producers were chasing every bid out there, yet stocks today sit roughly 100,000mt higher compared to last year. Yet last year it sat in the hand of producers, today most volumes are owned by either end users or traders with deep pockets. In the same week last year, spot butter sat at €5,450. Today spot is offered at €3,875, without many buyers. Yet sentiment amoung producers is calm and relaxt, with no real pressure. It makes sense that 10,000mt of stocks are losing roughly € 1.000.000 value each couple of days gives more sleepless nights than 1000mt bouncing up and down € 50.000 in value.
The data however says more butter is still going onto the pile. Last year 2025, in September, Germany produced 24% more butter than in September the year before. Critics will say that compares a strong year against a weak one, and that's fair. But last week's German numbers show 1.4% more milk than last year and another 13% more butter production. That's a strong year against a strong year.
Still, call a producer and offer to help move 500 mt of butter, and most will politely say no thanks. After six months of sideways trading on spot between € 3800 and € 4200 for butter, with no sign that the sideways range is about to break, holding stock a bit longer feels safe. Last year, missing a week of sales could cost €200–€300/mt (prices fell from almost €7,200 to €4,000 in a little over 16 weeks). Today, holding off might even gain you €100/mt. When the downside is that small, waiting is comfortable. Producers used to fear losing tens of millions by selling too late. Now they rightfully can expect to gain a little by keeping their cool.
For butter to turn bullish, though, buyers need to see it differently too, and so far they don't. Just like last year, buyers are eager to lock in forward contracts. Last year around this time buyers locked in butter between € 5000 and € 6000 for the full 2026, for 2027 they can do the same between € 4000 and € 5000. They have no reason to gamble on even lower prices. They're afraid of a butter bounce and of losing €1,000/mt, as they did in 2024. We don't expect that fear to fade. Every uptick in cream, every move up in futures and every dip in milk collection sends buyers to the market and makes sellers hold back.
Cheese: More cheese, higher prices
Cheese tells a similar story. Production has been rising for weeks, and Germany alone reports 5% more cheese YtD. But price-wise, the cheese market looks a lot different than a year ago. In a positive way. In October 2025, Q1 cheese traded between €2,800 and €3,000. Today, we'd argue an offer today at €3,500 would sell immediately, whatever the product. Spot prices traded between €2,950 and €3,150 in the same period last year. The strange opposite today v.s. last year? There's more cheese than, yet prices are about €400–€500 higher.
Every forecast points to more cheese. Producers also have an incentive to make whey, so the cheese price matters less than the price they get for the whey streams. More production and a steady incentive to produce should lead to excess stock. This year, though, the market seems to have adjusted by just the right amount. Forward sales have been good, and domestic and export demand have been strong enough to absorb the extra volume. As in liquids and butter, producers are relaxed and we see no real pressure.
Last year the quickly declining cheese prices felt like a reaction to the even faster-falling butter market. With butter prices stable, the sentiment around cheese prices is more or stable as well. That either makes last year's drop an overreaction or today's stable prices a denial.
The one risk we see is a slowdown in cheese exports. It isn't visible in the statistics yet, but we hear it in conversations. Prices may need to drop back towards last year's levels to get the occasional export boost the market needs. But every time the EU cheapens up for the world market, the volume gets absorbed and prices recover quickly. Knowing that outlet is probably still there keeps sellers at ease.
Powders: The one that actually flipped
For powders, the picture could hardly be more different. In Drowning in Milk we reported SMP below €2,000 and partners were joking about intervention bags again. Today SMP trades between €3,100 and €3,300. That's more than €1,000 higher in less than a year.
Powder had traded sideways for 24 months or more, and at that moment nobody believed prices could ever recover. Further down the curve, prices even dropped to €1,800. In hindsight, that's exactly where the bull market began. At that point you couldn't find a single partner who was bullish on SMP. SMC was available for almost nothing, production costs had dropped towards €1,200, and producers, end users and traders had all given up on a recovery. The outlook was dark, black and well below €2,000. Producers were selling into every decent bid, traders were shorting the market, and buyers almost everywhere were running their stocks down so they could refill at low prices. When that happens, a market gets very short very quickly.
Powder also differs from butter and cheese in one important way. Demand grew more than many expected, and production shrank more than most realised. SMC wasn't cheap last spring because nobody needed it. It was cheap because there wasn't enough capacity to dry it. Lower production capacity, higher demand and every key stakeholder short: the perfect recipe for a squeeze. Now sellers and buyers both see the market differently. Sellers have no stock, no pressure and a good forward book. Buyers have covered their shorts, contracted less volume forward, and face a trader market that, until a few weeks ago, had no long position to sell. The sales side holds a bit of product, the buy side needs a whole lot more we feel.
Final Note: Same milk, different minds
So, to our reader: is the market still drowning in milk? On paper, more or less, yes. There's more milk, more butter and more cheese than a year ago. The fundamentals haven't changed that much. How the people in the market see them has.
Last year, the same water came with a falling curve. Every day of waiting cost money, and fear drove every decision. Today it comes with a flat curve. Waiting costs a lunch, patience gets rewarded, and nobody chases bids. The water level is roughly the same. What changed is that nobody is afraid of drowning anymore.
Powder shows how fast that can turn. When everyone was on the same side, convinced prices could only go down, the market ran out of sellers before it ran out of milk, and SMP went from below €2,000 to above €3,000 in less than a year. Butter and cheese aren't there. The calm we see today is real, but it rests more on sellers' expectations the market can tighten, not on tight balance sheets. Butter buyers are still nervous, and cheese exports are quietly slowing, so those expectations can shift faster than any milk collection figure.
Markets rarely turn when the milk changes. They turn when minds change. And to the reader who liked a post from 11 months ago: thank you. You reminded us that the numbers were never the whole story.
The weekly report
Get it before it is anywhere else
Every market report, straight to your inbox the moment it is written. Butter, cheese, powder, liquids — pick what you actually trade.
Roughly weekly · Free · Unsubscribe any time